Personal Loan in UAE with 3000 Salary What You Need to Know
You earn AED 3,000 a month. You need a loan. And every bank you’ve walked into has told you the same thing: “Sorry, minimum salary requirement is AED 5,000.”
That used to be the end of the conversation. But in late 2025, the Central Bank of the UAE removed the mandatory minimum salary threshold . For the first time, earning AED 3,000 doesn’t automatically disqualify you. But here’s the catch banks still decide who they lend to. The rule changed, but the game didn’t get easier.
Safety Note: UAEfinbiz is an informational guide only and does not have access to your bank account or personal information. Never share your Emirates ID, salary certificate, bank statements, or OTP with any third-party website or individual claiming to process loans. Always apply directly through official bank channels or licensed financial institutions. Verify all terms, rates, and fees directly with the bank before signing any agreement. For verified information on loan regulations, visit the official Central Bank of the UAE website at www.centralbank.ae .
What Changed — And What Didn’t
The Central Bank scrapped the AED 5,000 minimum in November 2025 . But it didn’t say “everyone gets a loan.” It said banks can now assess borrowers based on affordability, not just income .
That means your AED 3,000 salary doesn’t automatically qualify you. It means you’re now in the game — if you meet the other criteria.
The rules that still apply:
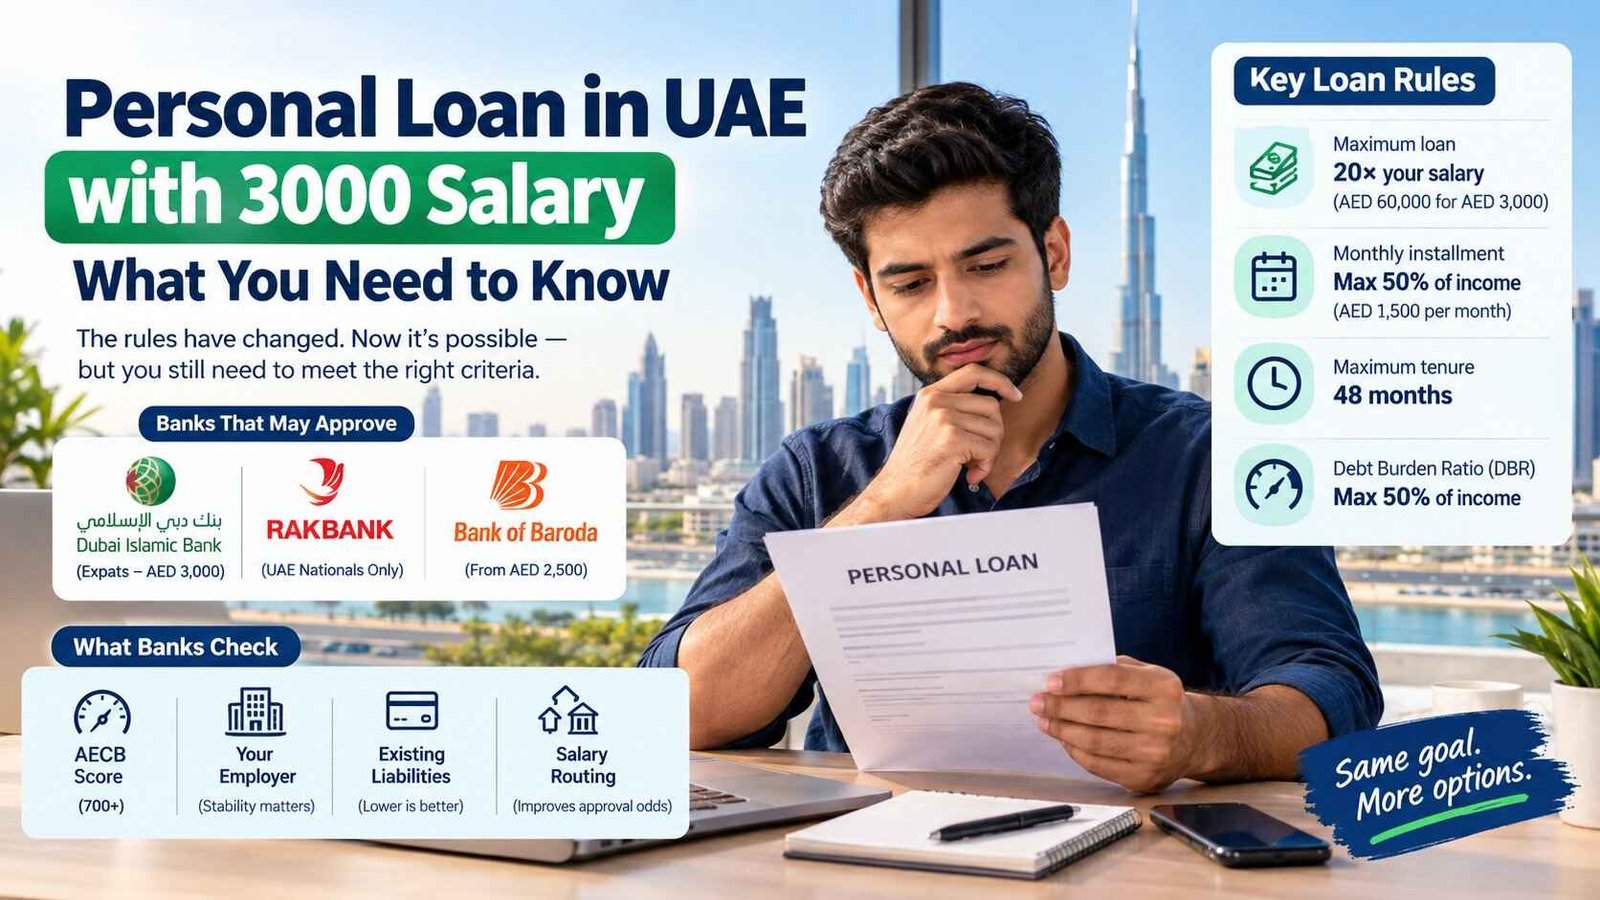
Maximum loan: 20 times your monthly salary. For AED 3,000, that’s AED 60,000 .
Maximum monthly installment: 50% of your gross income. That’s AED 1,500 per month, no exceptions .
Debt Burden Ratio (DBR): Your total debt payments (including this loan) cannot exceed 50% of your income .
If you already have a car loan or credit card payments, those count against you. If your DBR is already at 45%, you have almost no room for a new loan — regardless of what you earn.
Which Banks Actually Approve AED 3,000 Salaries
Not every bank that says “low salary loans” actually lends at AED 3,000. Here’s who does.
Dubai Islamic Bank (DIB) — Most Accessible for Expats
DIB is currently the most accessible mainstream lender for AED 3,000 earners, especially expatriates . The minimum salary requirement is AED 3,000 — but with a condition: salary transfer is mandatory .
Key facts:
- Minimum salary: AED 3,000
- Maximum finance: Up to AED 2 million for expats (subject to DBR)
- Available to non-salary transfer customers at higher salary thresholds
- Sharia-compliant profit rates
If you’re an expat earning AED 3,000, DIB is your most realistic starting point. But you need to transfer your salary to them .
RAKBANK — UAE Nationals Only
RAKBANK offers a AED 3,000 minimum salary loan, but only for UAE Nationals .
Key facts:
- Minimum salary: AED 3,000 (UAE Nationals only)
- Interest rates: 4.99% to 19.99%
- Loan amount: Up to 20 times salary
- Salary transfer required
- Employer must be on RAKBANK’s approved list
If you’re an expat, this option isn’t available to you. If you’re a UAE National, it’s one of the most competitive low-salary loans on the market .
Bank of Baroda — Lowest Threshold
Bank of Baroda accepts applicants earning as little as AED 2,500 — the lowest formal threshold in the UAE market . Unlike most banks, its loan cap isn’t strictly tied to salary multiples, though affordability assessments still apply .
This makes it relevant if you earn slightly below AED 3,000 or want a modest loan without premium pricing .
DIB FlexiSalary — Instant, Small Amounts
If you need a small amount quickly and don’t want to go through a full loan application, DIB’s FlexiSalary is a short-term facility available through the app .
Key facts:
- Amount: Up to AED 13,000
- Minimum salary: AED 2,000
- Tenure: 30–60 days
- Approval: Instant, funds within 30 minutes
- Available only to pre-approved DIB customers
This isn’t a traditional personal loan — it’s a short-term salary advance. But for urgent small expenses, it’s faster than any bank loan.
What Banks Actually Check (Beyond Salary)
Your AED 3,000 salary gets you past the first filter. But approval depends on four things you can control :
1. Your AECB Score
The Al Etihad Credit Bureau tracks your repayment history. A score above 700 is strong. Missed payments stay on your record for years .
2. Your Employer
Banks categorize employers by stability. Government, semi-government, and multinational companies get the best treatment. Free zone companies and SMEs face stricter scrutiny .
3. Your Existing Liabilities
Every loan and credit card you have reduces your borrowing capacity. If your DBR is already at 40%, you have almost no room .
4. Salary Routing
Banks prefer applicants who transfer their salary to them. If your salary goes to another bank, your options shrink or your rate goes up .
How to Improve Your Chances
Reduce existing debts first. If you have a small credit card balance, clear it before applying. Lower DBR = better approval odds .
Transfer your salary. Banks like DIB and RAKBANK require it. Even if a bank doesn’t require it, salary transfer improves your rate and approval chances .
Don’t apply everywhere at once. Each application triggers a credit inquiry. Multiple inquiries signal desperation and hurt your score .
Choose the right bank. DIB is your best bet as an expat. RAKBANK is for UAE Nationals. Bank of Baroda accepts lower incomes. Don’t waste applications on banks that won’t consider you.
FAQ’s
Can I get a personal loan in UAE with AED 3,000 salary?
Yes, but options are limited. DIB accepts expats with AED 3,000 salary (with salary transfer), and RAKBANK accepts UAE Nationals with AED 3,000 salary. The Central Bank removed the mandatory AED 5,000 minimum, but banks still set their own thresholds and assess affordability.
Which banks offer personal loans at AED 3,000 salary in UAE?
DIB offers personal finance at AED 3,000 for expats (salary transfer required). RAKBANK offers it for UAE Nationals only. Bank of Baroda accepts salaries from AED 2,500. Most other banks still require AED 5,000+.
How much can I borrow with AED 3,000 salary in UAE?
Maximum loan is 20 times your salary, so AED 60,000. But your monthly installment cannot exceed 50% of your gross income — that’s AED 1,500 per month. If you already have other debts, your borrowing capacity is lower.
Do I need salary transfer to get a AED 3,000 salary loan?
For DIB, yes — salary transfer is mandatory for the AED 3,000 minimum. Without salary transfer, DIB’s minimum rises to AED 6,000–8,000. RAKBANK also requires salary transfer for UAE Nationals. Without salary transfer, your options are extremely limited at this income level.
What is the DBR limit for AED 3,000 salary loans?
Your Debt Burden Ratio cannot exceed 50% of your gross monthly income. For AED 3,000 salary, that means total monthly debt payments cannot exceed AED 1,500. If you have existing loans or credit card payments, those count toward this limit.
Can I get a loan with AED 3,000 salary without salary transfer?
It’s extremely difficult. Most banks that accept AED 3,000 salaries require salary transfer as a condition. Without salary transfer, you’d need to earn AED 6,000–8,000+ to qualify at most banks. Digital lending apps may be the only option without salary transfer.
What documents do I need for a AED 3,000 salary loan?
Typically: Emirates ID, passport with visa, salary certificate (dated within 30 days), 3-6 months bank statements, salary transfer letter, and AECB consent form. Some banks also require a security cheque.
Is it better to wait until I earn more before applying?
It depends. If you need funds urgently and meet DIB’s criteria (salary transfer, good AECB score, DBR below 50%), applying now is possible. But if your DBR is already near the limit or your credit score needs work, waiting and improving your profile may get you better rates and higher amounts.